inflearn logo

Accounting and Fair Value Valuation of Convertible Financial Products

A single convertible bond contains not just one debt instrument, but multiple rights held by different owners. This course begins by interpreting the economic meaning of those rights and follows through in one continuous flow to determining the appropriate accounting treatment and reviewing valuation reports.

11 learners are taking this course

Level Intermediate

Course period Unlimited

Accounting
Accounting
Financial Management
Accounting
Accounting
Financial Management

What you will gain after the course

  • Read the issuance terms of convertible financial instruments in terms of the rights involved, and determine whose right each embedded option is and what economic significance it has.

  • Directly determine how to divide a single contract into multiple accounting units, what qualifies as a liability or equity, and complete the financial statement closing process.

  • We examine whether the outputs in the valuation report received align with the accounting unit and issuance terms, and whether the methods and input variables are appropriate.

  • Learn how to document the basis for decisions and reviews in official records.

From classification and recognition to LSMC measurement

The confusion in convertible financial instrument practice usually starts in one place: treating two different questions as one.

  • (Accounting’s question) As for this right, which accounting units should it be divided into, and its fair value be recorded in which accounts and at what amounts?

  • (Financial engineering question) For each accounting unit, how much is its fair value measured at—using a valuation model that incorporates the contractual terms

Recommended for these readers

Issuers/investors практиitioners

Those who work at companies that have issued/invested in convertible financial instruments or are reviewing an issuance/investment and need to make their own classification and measurement judgments

Auditors

Those who need to revisit the company's judgments and review external valuation reports

Valuation practitioners

Those who are familiar with models but want to confirm which accounting unit their output is assigned to

After completing the course,

  • From the rows of the issuance terms table, you can identify how many rights are included and who owns each right.

  • Why refixing breaks fixed-for-fixed, allowing you to determine whether there are three or four accounting units as a result

  • why issuer calls and third-party calls are treated differently,and explain how separate recognition differs from asset recognition

  • From issuance to maturity, you can prepare journal entries for each stage of the life cyclefrom both the issuer’s and investor’s perspectives

  • Understand where lattice-based models run into limitations and how LSMCsolves them through its underlying logic

  • You can identify the scope, methodology, input variables, and sensitivity in the valuation report you receive and document the basis in your working papers

Features of this course

Please introduce the key features and differentiators.

핵심특징

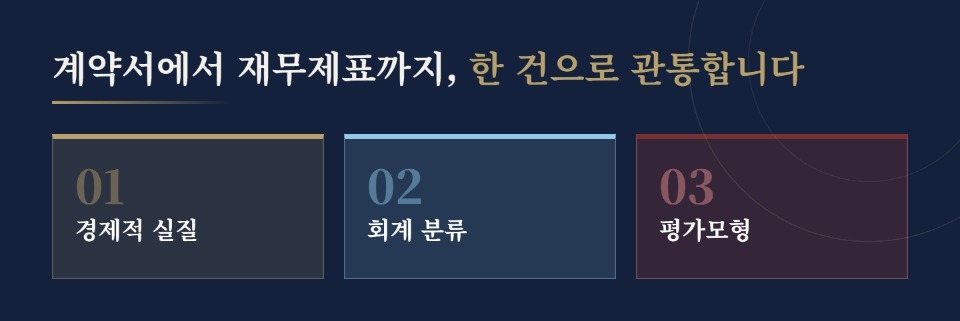
From Contracts to Financial Statements

This is explained using a case study of a listed company’s convertible bond issuance.

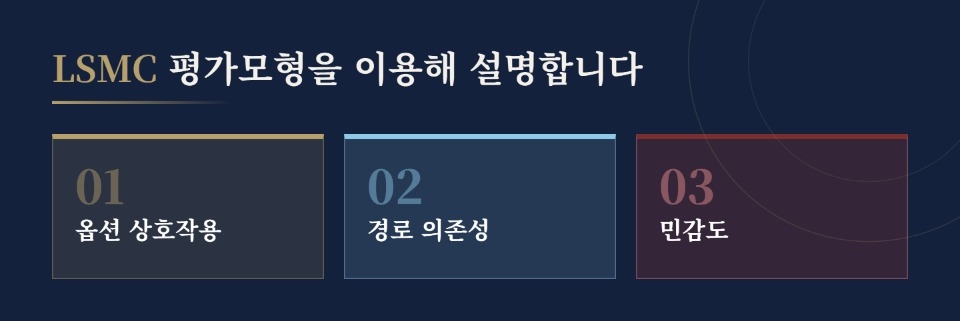
Using the LSMC valuation model

Explain how option interactions and path dependence are incorporated into valuation models, using sensitivity analysis.

You will learn this kind of content.

Understanding the Product

The economic substance of option clauses
What each conversion right, put, and call allows whom to give and receive what.
Read not as clauses, but as economic substance.

Accounting classification

Accounting classification under the applicable standard
What accounting units to divide it into,
which items are liabilities and which are equity,
and how they are presented in the financial statements—judgment

Fair value measurement

Valuation models that reflect economic substance
Whether the valuation model reflects the contract structure,
whether the input variables are appropriate,
and whether the valuation results are consistent with the contract structure—assess

Creator of this course

  • Certified Public Accountant · Master of Engineering (KAIST)

  • Drawing on experience working with both accounting and financial engineering, I have organized practical issues that arise at the intersection of the two fields.

  • Book: “Accounting and Fair Value Valuation of Convertible Financial Instruments — From Classification and Recognition to LSMC Measurement”

Do you have any questions?

Q. Can't we just read the accounting standards?

You must read the standards. The problem is that the standards were not written with Korean-style CBs in mind. They are not provisions written for combinations of clauses such as market-price refixing, a put option exercisable by a third party designated by the issuer, and mandatory holding periods.
So simply transcribing the provisions does not lead to a conclusion. You must examine why fixed-for-fixed is required and whether its rationale is upheld by this clause. Rather than listing provisions, this course presents the order of determination.

Q. Our company has issued RCPS. Would a convertible bond course be helpful?

That is how it works. The order of determination remains the same even when the product changes, and what differs is the step in that sequence at which the determination branches. RCPS is determined at the substance of the host contract, the first gateway; BW at the exercise consideration; and EB at the underlying asset. These are addressed by product in Section 2.5.
However, the case study follows a single convertible bond transaction throughout. If we included more products, the cases would become scattered, making it difficult to follow the sequence. The journal entries for the issuance and period-end closing of RCPS are covered separately.

Q. I am a valuation practitioner. Can I skip the accounting section?

Valuation models used overseas may not reflect the contractual terms of convertible financial instruments issued in Korea, because such terms are not common overseas. I believe what Korean valuation practitioners actually need is Sections 1 and 2.

Notes Before Taking the Course

Learning Materials

Prerequisite Knowledge and Important Notes

  • K-IFRS Basics

  • Basic concepts of options

  • We do not provide regression equation derivation, basis function selection, path generation algorithms, or code distribution.

Recommended for
these people

Who is this course right for?

  • Company Finance and Accounting Team

  • External Auditor (Certified Public Accountant)

  • Evaluation Practitioner

Need to know before starting?

  • Basics of K-IFRS 1109

  • Basic Concepts of Options

Hello
This is GB Cheon

Drawing on my experience in venture capital, where I managed investments in unlisted startups via Convertible Bonds (CB) and Redeemable Convertible Preferred Stock (RCPS), and having directly analyzed and evaluated a variety of equity-linked financial products, I continue to conduct applied research bridging accounting and financial engineering.

Curriculum

All

18 lectures ∙ (55min)

Course Materials:

Lecture resources
Published: 
Last updated: 

Reviews

Not enough reviews.
Please write a valuable review that helps everyone!

Similar courses

Explore other courses in the same field!

Limited time deal ends in 1 days

$23,100.00

30%

$26.40